

Market Outlook
| October 30, 2026 | 1 Month |
1 Year |
|
| Rupees per Dollar | 94.96 | 95.83 | 88.77 |
| Oil (dollars per barrel) | 117.64 | 103.53 | 65.07 |
| Retail inflation (CPI) | 5.54% (September) | 4.83 | 1.41 |
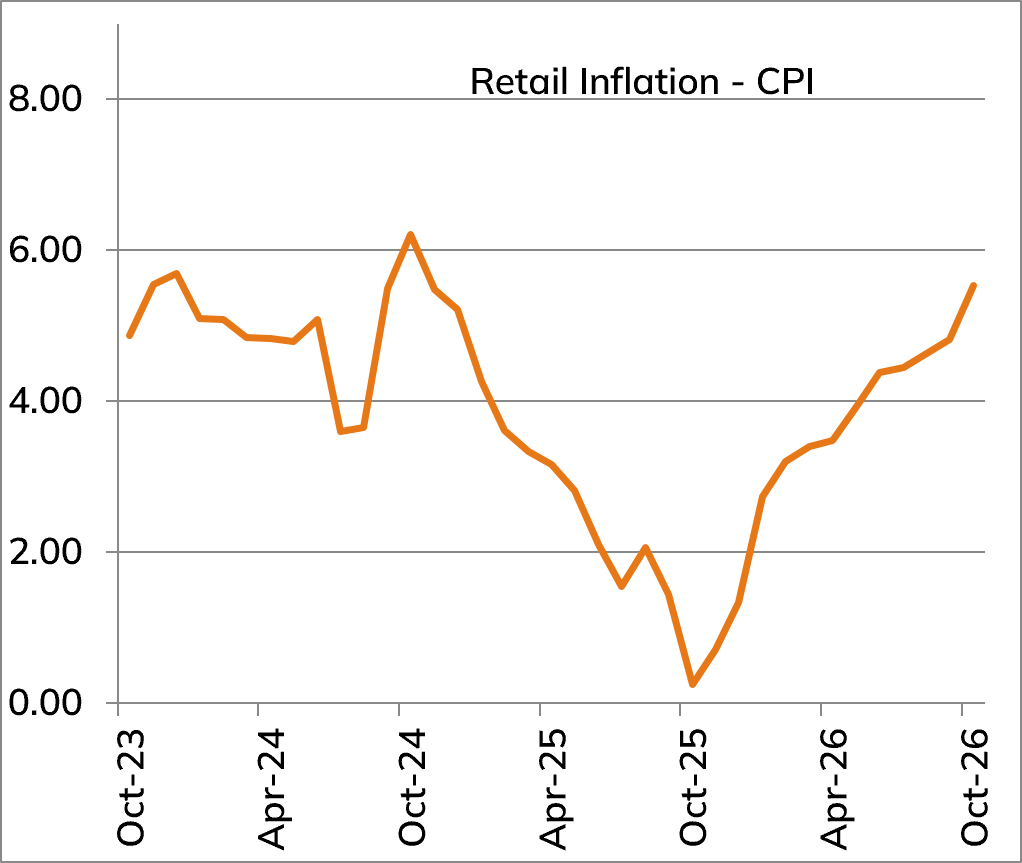
- Crude oil prices remained volatile due to ongoing geopolitical tensions in the Middle East. Rupee recovered from its September lows, ending October at `94.96 per dollar, aided by RBI's aggressive intervention including a special dollar window for state-run oil refiners and regulatory measures to curb speculative positioning.
- US Fed kept the policy rate unchanged at 3.75% - 4.00%. Fed also noted that further rate hikes may be warranted if inflation remained above 2% target. Debt market uncertainty arising out of Democratic sweep of both the House and Senate in the November 2026 US midterm elections will be a key monitorable. Global rate hike cycles across major central banks continue to exert upward pressure on emerging market bond yields.
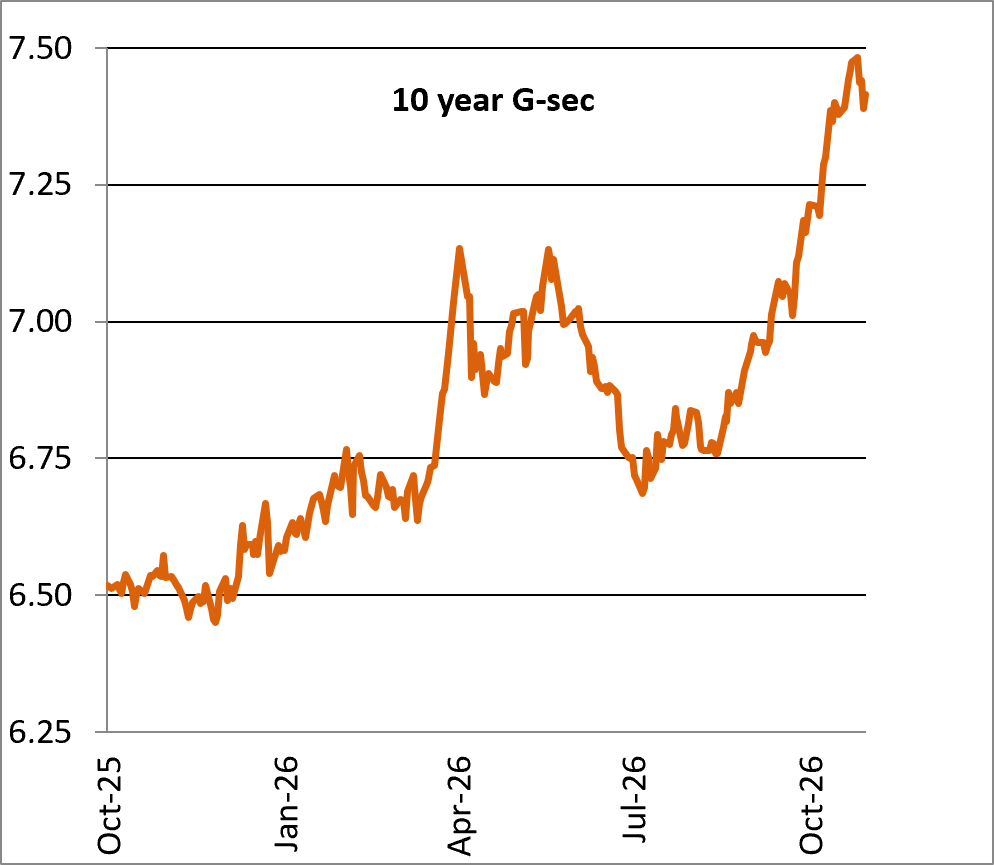
- Elevated crude oil prices, weakening rupee and inflationary impact of weak monsoon are expected to keep domestic CPI elevated and bond yields under pressure. We expect RBI to hike rates by 50 bps in the second half of FY27 and the 10 year benchmark yield to trade in the 7.00%–7.40% in the near term, with upside risks from crude and food inflation.
| Index | 1 month (%) | 1 year (%) | 3 years (%) |
|---|---|---|---|
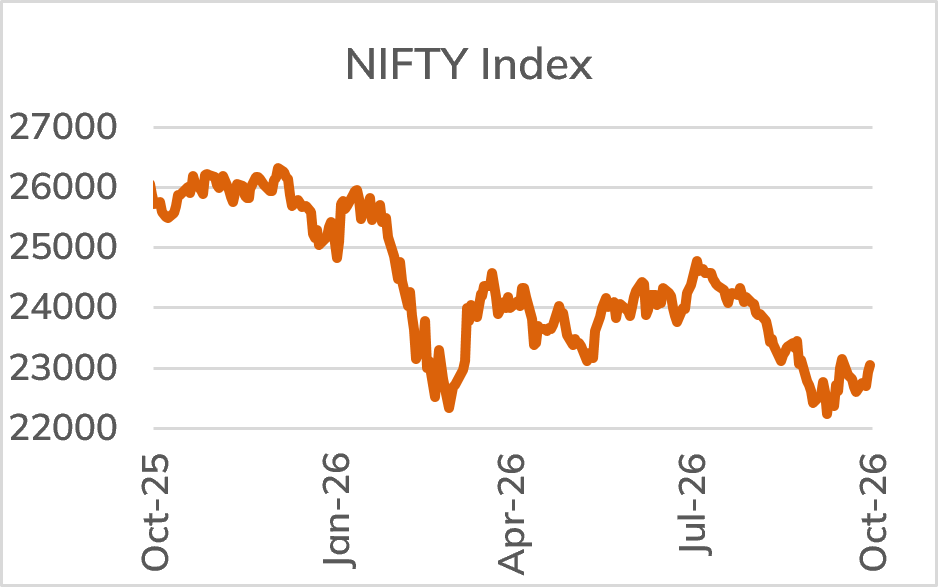
| NIFTY50 | 1.9 | -10.4 | 6.5 |
| BSE100 | 0.9 | -9.3 | 7.8 |
| NIFTY500 | -0.8 | -7.6 | 9.2 |
| NIFTY Midcap100 | -3.4 | -4.2 | 13.8 |
At October 31, 2026
Nifty was up 1.9% for the month of October 2026
- Despite surging crude prices and rising geopolitical tensions large caps outperformed midcaps
- Within BSE 100 index, Technology/Telecom outperformed while Metal & Minerals/Finance underperformed the broader market
We maintain our positive stance over the short as well as medium term
- Q2 FY27 Corporate earnings (so far) are largely ahead of expectation
- The shift of balance of power in US bodes well for Indian Macro
- RBI MPC revised upwards its FY27 real GDP projection by 40bps to 7.1% YoY, following a strong 7.8% YoY growth
- Nifty’s FY27 P/E at 19x, is below 5-year average and trading at attractive valuations
Over the medium term, we expect following drivers for growth to play out:
- Continued fiscal and monetary support and expanding Free Trade Agreements (FTAs)
- Strengthening manufacturing ecosystem through Production Linked Incentives (PLI), indigenization and supply-chain diversification
Market consensus for Nifty earnings is at mid-teens CAGR over FY2026-28
IL/COMP/DOC/Nov/2026/911/1440
