India's rapid economic progress has created unprecedented opportunities for growth and prosperity. With advancing healthcare and improved living standards, Indians are living longer, fuller lives than ever before. While this extended lifespan brings joy and new possibilities, it also demands careful financial planning to ensure you can embrace your retirement years with complete peace of mind without worrying about income security.

Introducing ICICI Life Guaranteed Indexed Pension

A retirement solution designed around your unique needs and comfort level. This plan gives you the freedom to opt for:

A 100% guaranteed income for complete predictability and security, or

B. Craft your own blend by combining guaranteed income with market-linked income to capture growth potential and beat inflation.

Key features

  • Guaranteed income1 that is fixed for life
  • Additional income depending on performance of index2 - NIFTY 50 TRI
  • Flexibility to choose proportion of guaranteed income and index-linked income
  • Option to take income for single life or joint life
  • Financial security for your family even in your absence, with the Waiver of Premium feature under Joint Life4
  • Flexibility to advance future income as lump sum5
  • Flexi Save Wallet8 to save and grow income instead of taking as payouts
  • Complimentary health management servicesV. To know more click on this link
  • Premiums returned to the nominee3

Steps Towards Saving For Your Retirement Goals

Step 1 – Choose how much premium you want to pay and for how long

Step 2 – Choose guaranteed proportion you want.

Step 3 – Choose annuity frequency and when to start receiving the annuity.

Step 4 – Pay premiums for the chosen duration and enjoy guaranteed lifelong annuity1.

Benefits under the plan

Life Annuity with Return of Purchase Price

In this option, the Annuitant will receive annuity in arrears as per chosen annuity payment frequency. Such annuity will be paid for life of the Annuitant(s) on single or joint life basis, as chosen, for as long as Annuitant(s) are alive. In this variant:

Annuity instalment = Guaranteed Annuity instalment + Variable Annuity instalment

Here,

1. Guaranteed Annuity1 = Guaranteed Proportion x Base Annuity Amount x Annuity Modal Factor ÷ Annuity Frequency Factor, where Guaranteed Proportion, can range from 60% to 100%, in multiples of 10%

2. Variable annuity instalment will vary as per the returns of Index. The applicable Index for benchmarking of variable annuity2 offering shall be NIFTY 50 Total Returns Index. For detailed calculation refer brochure.

Death Benefit:

A. During Deferment Period (if any)

Death Benefit3 for Single Life or Joint Life option on death of last survivor, is equal to higher of:

  • 105% of Total Premiums Paid up to the date of death, and
  • Surrender Value payable as on date of death

B. For Immediate Annuity option or after Deferment Period (if any)

Death Benefit3 is equal to Total Premiums Paid up to the date of death.

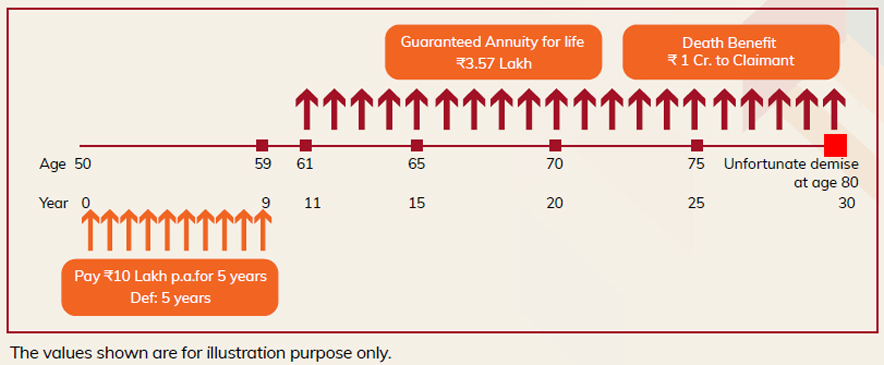
Scenario 1: Where Ms. Spoorti decides to get entre income as guaranteed and hence chooses guaranteed proportion as 100%

Premium Payment Term 5 years Deferment Period 5 years
Annual Premium ₹10 Lakhs Total Premiums Paid ₹50 Lakhs

The values shown are for illustration purpose only

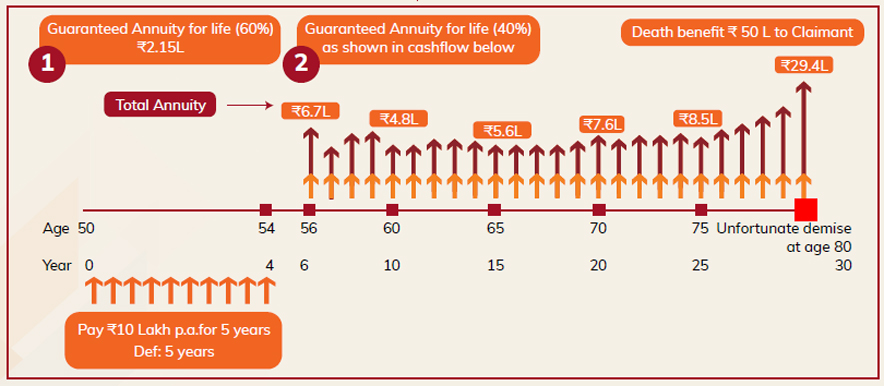
Scenario 2: Where Ms. Spoorti decides to take a part of the income and enjoy a potential upside by getting an index-linked income. She chooses guaranteed proportion: 60%

Premium Payment Term 5 years Deferment Period 5 years
Annual Premium ₹10 Lakhs Total Premiums Paid ₹50 Lakhs

The values shown are for illustration purpose only. The Variable annuity mentioned is indicative basis the past performance of NIFTY 50 TRI

Eligibility Criteria:

Annuity Variant Premium Payment Term Minimum/Maximum Deferment Period Minimum/Maximum age at entry Minimum Premium
Life Annuity with Return of Purchase Price Single Pay For Immediate Annuity: 0; 30/80 ₹ 5,00,000
For Deferred: 1 to 20
Limited Pay: 2 to 4 PPT to 20 ₹ 2,50,000
Limited Pay: 5 to 6 ₹ ₹ 1,00,000
Limited Pay: 7 and above ₹ 50,000
Life Annuity with Return of Purchase Price (POSP) Single Pay Immediate Annuity: 0 40/70 ₹ 5,00,000

* Above conditions are subject to maximum vesting age of 85 years (for Life Annuity with Return of Purchase Price)/ 80 years (for Life Annuity or Life Annuity with Return of Balance Purchase Price)

If the product is purchased as QROPS through transfer of UK tax relieved assets/ QOPS, the minimum vesting age will be 55 years.

The minimum guaranteed annuity amount shall correspond to the minimum single / annualised premium payable under the policy. The Annuity amount will depend on the Plan Variant chosen.

The maximum base annuity amount will be subject to the Board approved underwriting policy.

Additional Features:

A. Option to get liquidity with Annuity Advance option5

In case of financial emergencies, availability of lump sum funds becomes extremely crucial. Keeping this mind, the Advance Annuity option5 provides you the flexibility under to avail a lumpsum in lieu of future guaranteed Annuity1 payouts, as applicable. This option is available only with the “Life Annuity with Return of Purchase Price” variant. For more details refer brochure.

B. Flexi Save8 Wallet to save and grow income instead of taking as payouts

At any point during the Annuity payout period, provided at least one full year’s annuities have been paid out, You/Annuitant(s) shall have an option to accumulate the total annuity amount (including the variable annuity2 amount, if any) with the Company instead of taking the annuity payout. This option can be exercised any time after at least one full year’s Annuities have been paid out. For more details refer brochure.

In case of death of the Annuitant(s) due to suicide within 12 months from the Date of commencement of the policy or from the date of revival of the policy, as applicable, the Claimant shall be entitled to 80% of the Total premiums paid till the date of death or the Surrender Value available as on the date of death whichever is higher, provided the policy is in force.

In case any annuity instalments have already been paid out, during the 12 months after the date of commencement of risk under the policy or date of revival, as applicable such amount already paid out shall be deducted from the amount payable on such death.

The Policy will terminate on making such a payment and all rights, benefits and interests under the Policy will stand extinguished.

  • Officially Valid Document (OVD) for identity and address proof
  • Recent Passport-size Photograph
  • Age Proof (if not established through OVD)
  • PAN (or Form 97, wherever applicable)
  • Payout Mandate – Bank account details
  • CDF - Customer declaration
  • Agent confidential report (Based on login source)
  • Passport (Applicable for NRI)
  • FATCA/CRS declaration (where applicable)
  • Any other document, as may be required by the Company on a case-to-case basis

Basic documents and verifications required for Claim Settlement

For processing a death claim under this Policy, We will require the following documents (as may be relevant) in case of:

  • Duly filled and signed Claimant Statement Form
  • Recent photograph of the claimant
  • Death Certificate issued by local government authority of the person insured in the policy (Annuitant(s))
  • Signed copy of photo identity proof of the claimant
  • Current Address proof of the claimant (Any one of the following: Aadhar Card, Valid Passport or Driver's License, Voters ID are considered as proofs)
  • Signed copy of PAN card / Form 97 of the claimant
  • Copy of cancelled cheque / bank statement / passbook of the bank account of the claimant where payment needs to be transferred.

Additional documents will also be required, depending on the type of death, for faster processing of your claim –

For deaths due to Natural/ Medical reasons:

  • Medico-legal / Medical cause of death certificate
  • Past medical records and treatment papers
  • All hospitalization records of the Life Assured such as:
    • Admission form
    • Indoor Case Papers (ICPs)
    • Discharge summary
    • Diagnostic test reports such as USG, Pathology / Lab reports etc.
  • Duly filled in Treating Doctor Certificate
  • Duly filled in Medical/ Hospital Attendant Certificate

Death due to any other reason:

  • Medico-legal cause of death certificate
  • First Information Report (FIR) from the police authority
  • Inquest/ Panchnama Report
  • Final police investigation report
  • Post Mortem Report (PMR) issued by the hospital
  • Viscera / Chemical examination report
  • Newspaper Cutting, if any
  • Driving License (of the Life Assured driving the vehicle in case of death due to a road accident)
  • Hospitalization / treatment records if any
  • Duly filled in Medical/ Hospital Attendant Certificate
  • Duly filled in Employer Certificate (only if Life Assured was a salaried individual)
  • Any other documents or information as may be required by the Company for processing of the claim depending on the cause of the claim
  • The Company reserves the right to call for additional information, documents or particulars, in such form and manner as the Company would prescribe, and the Benefits would be paid only after receipt of such additional information, documents or particulars.

Claim payments are made only in Indian currency in accordance with the prevailing Exchange control regulations and other relevant laws and regulations in India. In case the Claimant is unable to provide any or all of the above documents, in exceptional circumstances such as a natural calamity, the Company may at its own discretion conduct an investigation and may subsequently settle the claim.

What is ICICI Life Guaranteed Indexed Pension?

ICICI Life Guaranteed Indexed Pension is an annuity product designed to provide income for life. It offers Life Annuity with Return of Purchase Price variant which combines a guaranteed annuity component with an index-linked variable annuity component. Thus, it helps in giving potential upside in income through index-linked annuity while also giving comfort of a guaranteed annuity amount every year.

How does the annuity work?

The annuity will comprise of two components:

  • Guaranteed Annuity – provides the guaranteed portion of the annuity.
  • Variable Annuity – an index-linked component linked to the performance of the publicly available index, NIFTY 50 TRI

How is variable annuity computed?

In Life Annuity with Return of Purchase Price variant:

Annuity instalment = Guaranteed Annuity instalment + Variable Annuity instalment.

Guaranteed Annuity instalment is as per the prevailing annuity rate during purchase

Variable Annuity Instalment will vary as per the returns of Index.

Variable Annuity instalment = Variable Annuity Amount x Annuity Modal Factor ÷ Annuity Frequency Factor, where the Variable Annuity Amount (VAA) is set as:

VAA = (1 - Guaranteed Proportion) x Base Annuity Amount x {Premium accumulation at Net Index Return (NIR) ÷ Premium accumulation at Assumed Interest Rate (AIR)}

In case You have opted for non-monthly mode as Annuity payment frequency, the Annuity Instalment due will be as per the formula above.

In case You have opted for monthly mode as Annuity payment frequency, the first Annuity Instalment due in any Policy Quarter will be based as per the formula above. This monthly Annuity amount for the immediate next two annuity payouts shall remain same as the first annuity payout for the remaining Policy Quarter.

What is the index used?

NIFTY 50 TRI as the benchmark index.

Is the Annuity payable for life?

Yes. The annuity is payable for life. The guaranteed annuity component is fixed for life while the variable annuity is linked to the performance of the index.

Is the product available for joint life4?

Yes. The plan can be availed on single life or joint life basis.

Who can be covered as the secondary annuitant under Joint Life?

The permitted Joint Life relationships are spouse, parent, sibling or child

What is the Death Benefit?

1. Death Benefit3 for Single Life Policies:

i. In the event of death of the Annuitant during the Deferment Period, the Death Benefit payable by the Company to the Claimant shall be the higher of

  • 105% of Total Premiums Paid up to the date of death, or
  • Surrender Value payable as on date of death.

ii. In the event of death of the Annuitant under after the Deferment Period for Deferred Annuity option or under Immediate Annuity option, Death Benefit payable by the Company to the Claimant shall be equal to Total Premiums Paid up to the date of death of the Annuitant.

2. Death Benefit3 for Joint Life Policies:

Death benefit is payable only on death of last surviving Annuitant.

i. In the event of death of the last surviving Annuitant during the Deferment Period, the Death Benefit payable by the Company to the Claimant, shall be higher of:

  • 105% of Total Premiums Paid up to the date of death, or
  • Surrender Value payable as on date of death

ii. In the event of death of the last surviving Annuitant after the Deferment Period for Deferred Annuity option or under Immediate Annuity option, Death Benefit payable by the Company to the Claimant shall be equal to Total Premiums Paid up to the date of death of last surviving Annuitant.

What are the boundary conditions?

Annuity Variant Premium Payment Term Minimum/Maximum Deferment Period Minimum/Maximum age at entry Minimum Premium
Life Annuity with Return of Purchase Price Single Pay For Immediate Annuity: 0; 30/80 ₹ 5,00,000
For Deferred: 1 to 20
Limited Pay: 2 to 4 PPT to 20 ₹ 2,50,000
Limited Pay: 5 to 6 ₹ 1,00,000
Limited Pay: 7 and above ₹ 50,000
Life Annuity with Return of Purchase Price (POSP) Single Pay Immediate Annuity: 0 40/70 ₹ 5,00,000

* Above conditions are subject to maximum vesting age of 85 years (for Life Annuity with Return of Purchase Price)/ 80 years (for Life Annuity or Life Annuity with Return of Balance Purchase Price)

If the product is purchased as QROPS through transfer of UK tax relieved assets/ QOPS, the minimum vesting age will be 55 years.

The minimum guaranteed annuity amount shall correspond to the minimum single / annualised premium payable under the policy. The Annuity amount will depend on the Plan Variant chosen.

The maximum base annuity amount will be subject to the Board approved underwriting policy.

What is Advance Annuity5?

Advance Annuity Option under the ‘Life Annuity with Return of Purchase Price’ variant, policyholder / annuitant(s) can opt for a lump-sum payout by taking a preset portion (1% to 99%) of the up to next 5 years of future guaranteed annuities at present value.

On exercise of this option, the policyholder/ annuitant(s) shall receive the ‘Advance Annuity Amount’ immediately as lump sum equal to present value of a preset proportion of the guaranteed annuities payable over the chosen ‘Advance Annuity Period’. The Advance Annuity Period can be chosen in integral years and can be any whole number between 1 and 5. The preset proportion can be between 1% and 99% (multiple of 1%) and must be chosen at the time of exercise by the policyholder/ annuitant(s).

What is Flexi Save8 Option?

At any point after Annuity Commencement Date, provided at least one full year’s annuities have been paid out, there is an option to accumulate the total Annuity amount with the Company instead of Annuity payout. This is called as “Flexi Save Option” and these Annuities shall be transferred to “Flexi Save Wallet”. Upon crediting the Annuity instalments in the Flexi Save Wallet on the due date, the Annuities will be deemed to have been paid. The money within the Flexi Save Wallet will be accumulated with daily accrual of a loyalty addition at the Reverse Repo Rate published by Reserve Bank of India (RBI).

1 The income/annuity amount is guaranteed for life and payable either immediately or after the end of deferment period (if any), as applicable. Guaranteed Annuity is calculated as per the guaranteed proportion chosen.

2 This is applicable only in Life Annuity with Return of Purchase Price option where guaranteed proportion chosen is less than 100%.

3 Upon the unfortunate demise of the annuitant/both the annuitants, the nominee will receive the Death Benefit as applicable.

4 This is available under Joint Life option where the relationship between the Primary Annuitant and the Secondary Annuitant can be either spouse, child, parent, or sibling.

5 This option is allowed for ‘Life income with Return of Purchase Price’ variant, allowing the annuitant(s) to opt for a lump-sum payout in lieu of future guaranteed income/incomes, given at least one full year’s incomes have been paid out and there is no loan outstanding in the policy as on the date of exercise and Flexi Save option has not been exercised. Such lump sum will be equal to present value of a preset proportion (1% to 99%) of the Guaranteed Annuities payable over the next 1 to 5 years, as chosen by the policyholder. The maximum amount payable as ‘Advance Annuity Amount’ shall not exceed 50% of Total Premiums Paid.

8 The Annuitant(s) can opt to accumulate the total income amount in Flexi Save Wallet, provided one full year’s annuities have been paid out, provided there is no loan outstanding in the policy as on the date of opting in. The money within the Flexi Save Wallet will be accumulated with daily accrual at the Reverse Repo Rate published by Reserve Bank of India (RBI).

V The Annuitant(s) will get access to a carefully curated suite of health management & well-being services. These Services are applicable only if the policy is in force with all due premiums paid to date. The Annuitant(s) can enjoy these benefits from our ICICI Life Customer app. The Annuitant(s) will not be charged separately for availing of these services. These services may be availed throughout the policy, subject to prevailing eligibility criteria. Please refer to the policy brochure for the complete list of terms and conditions as applicable for availing the services.

ICICI Life Insurance Ltd. (formerly known as ICICI Prudential Life Insurance Co. Ltd.) IRDAI Regn No. 105. CIN: L66010MH2000PLC127837.. Registered Address: 1089 Appasaheb Marathe Marg, Prabhadevi, Mumbai - 400025. For more details on the risk factors, terms & conditions, please read the policy document. ICICI Life Guaranteed Indexed Pension. UIN: more details on the risk factors, terms & conditions, please read the policy document. ICICI Life Guaranteed Indexed Pension

ICICI Life Guaranteed Indexed Pension UIN:

ADVT: W/II/1285/2026-27

Back to Top